

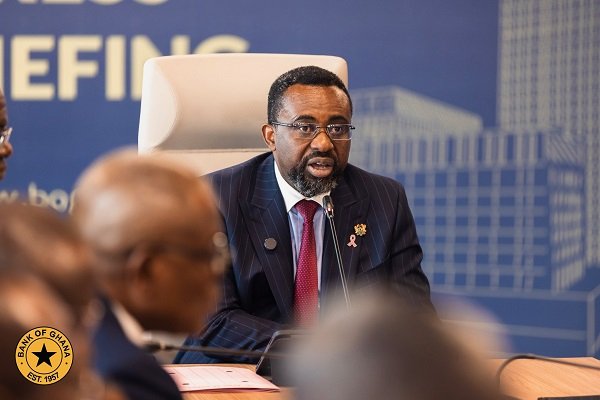
Bank of Ghana (BoG) Governor Dr Johnson Pandit Asiama has warned that credit risk in Ghana’s banking sector remains elevated despite improvements in banks’ financial performance, asset quality and capital positions. Corrections Policy
The warning highlights the need for financial institutions to maintain prudent lending practices as credit demand increases and borrowing costs decline.
Although the sector has recorded stronger balance sheets and a reduction in non-performing loans, the Central Bank says risks associated with lending remain a concern.
Dr Asiama made the remarks during the press conference following the 132nd meeting of the Monetary Policy Committee (MPC), where the Committee maintained the policy rate at 14 per cent.
The decision marked the third consecutive time the rate had been held at that level in 2026.
According to the Governor, Ghana’s banking industry remains solvent, profitable and liquid, with key financial indicators showing improvements over the past year.
However, the continued presence of elevated credit risk means banks must remain cautious when assessing borrowers and extending new loans.
The sector’s total assets increased by 20.5 per cent year-on-year to GH¢500.2 billion in August 2026.
The growth was supported by deposit mobilisation and an expansion in other funding sources, reflecting an increase in the resources available to financial institutions. Editorial Standards
Banks also recorded an improvement in their capital adequacy ratio, which rose to 19.1 per cent in August 2026 from 18.3 per cent in the same month of 2025.
The ratio measures a bank’s capital relative to its risk-weighted assets and provides an indication of its capacity to absorb potential financial losses.
Another positive development was the decline in the industry’s non-performing loan (NPL) ratio, which fell to 15.7 per cent from 20.8 per cent over the same period.
Non-performing loans are credit facilities for which borrowers have failed to meet repayment obligations for a specified period under applicable regulatory definitions.
A high NPL ratio can put pressure on banks because unpaid loans may require additional provisions, reduce earnings and limit the funds available for further lending.
Despite the improvement, the remaining level of problem loans underlines the importance of effective credit assessment, loan monitoring and recovery procedures.
Dr Asiama stressed that banks were expected to comply with the Central Bank’s guidelines on non-performing loans to strengthen confidence in the financial system.

Such compliance is important for protecting depositors, maintaining financial stability and ensuring that lending supports productive economic activity.
The warning comes amid a significant recovery in private-sector credit growth. According to the Governor, private-sector credit expanded by 35.5 per cent year-on-year in August 2026, compared with 13.3 per cent in August 2025.
In real terms, which account for the effect of inflation, growth increased to 29 per cent from 1.7 per cent over the same period.
The average lending rate also declined to 15.9 per cent in August 2026 from 24.2 per cent a year earlier.
Meanwhile, the 91-day Treasury bill rate fell to 5.4 per cent from 10.3 per cent.
Lower lending rates and an easing of banks’ credit conditions have helped stimulate borrowing by businesses and other private-sector participants.
Greater access to financing can support investment, working capital, business expansion and job creation.
However, faster credit growth also makes proper risk assessment particularly important.
If banks expand lending without adequately evaluating borrowers’ repayment capacity, they could face higher defaults and financial losses when economic conditions change.
A separate warning issued by the Bank of Ghana at a banking policy seminar also highlighted the risks of rapid credit expansion without sufficient assessment of borrowers.
The Central Bank cautioned that aggressive lending could expose banks to defaults, impairment charges and pressure on their balance sheets.
For businesses, access to credit remains essential for purchasing equipment, managing cash flow and expanding operations. Editorial Ethics & Independence
Yet sustainable lending depends on borrowers being able to repay their loans and banks maintaining appropriate standards when approving credit facilities.
The Central Bank’s position therefore reflects the need to balance stronger private-sector financing with safeguards against a renewed deterioration in loan quality.
Banks must consider borrowers’ income, cash flow, existing debt obligations and the risks associated with the sectors in which they operate.
The broader economic environment will also remain relevant to the outlook for credit quality.
Changes in inflation, interest rates, business activity and global financial conditions can affect borrowers’ ability to meet repayment obligations.
Although Ghana’s banking sector has recorded improvements in capitalisation, profitability and liquidity, continued supervisory oversight and responsible lending will be important in preserving those gains.
Dr Asiama’s warning serves as a reminder that stronger banking-sector growth must be accompanied by sound risk management.
Maintaining lending discipline, enforcing regulatory requirements and monitoring existing loans will be central to ensuring that expanding credit supports businesses and economic growth without undermining financial stability.