

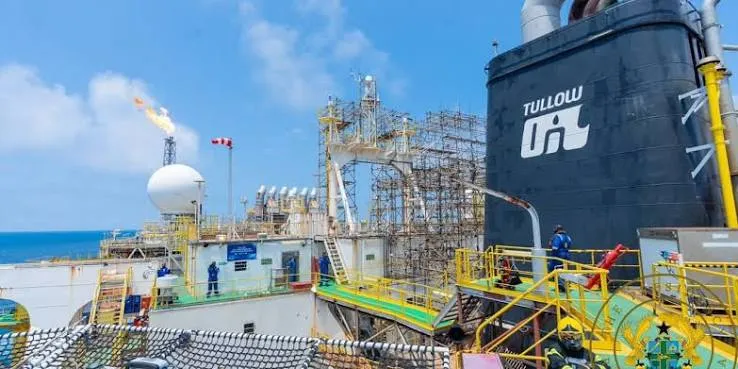
Ghana has won a major tax dispute against oil producer Tullow Oil after an international tribunal dismissed all claims brought by the company and upheld a US$393.09 million tax assessment issued by the Ghana Revenue Authority (GRA). Newscard
The decision marks a significant development in the government’s efforts to enforce tax obligations against companies operating in the country, while maintaining investment and production in Ghana’s petroleum industry.
In a statement issued on September 30, 2026, Finance Minister Dr Ato Forson announced that the tribunal had upheld the GRA’s assessment of US$393,091,993.70 in full.
The tribunal also ruled that the assessment did not breach Ghana’s Petroleum Agreements with Tullow, that the penalty imposed by the tax authority was properly applied and that the assessment was not time-barred.
According to Dr Forson, the tribunal further determined that the GRA’s enforcement action was lawful, rejecting the claims brought by the oil producer in the proceedings.
“The Tribunal ruled in favour of Ghana. It dismissed all claims brought by Tullow and upheld in full the Ghana Revenue Authority’s tax assessment of US$393,091,993.70,” the minister said.
He added that the tribunal found no breach of the applicable petroleum agreements and upheld the basis on which the GRA imposed the penalty.
The ruling reinforces the government’s position that businesses operating in Ghana must comply with the country’s tax laws and applicable legal requirements, irrespective of their size, ownership or economic significance. Editorial Standards
Dr Forson acknowledged the work of the Office of the Attorney-General, the GRA and Ghana’s external legal counsel, Foley Hoag LLP, in representing the country’s interests throughout the dispute.
He said the outcome affirmed the principle that all companies operating within Ghana’s jurisdiction are subject to the country’s laws.
“This outcome vindicates the position Ghana has maintained throughout: that every company operating in this country, regardless of its size, is subject to the laws of Ghana,” he stated.
The government said the ruling comes as Ghana and its petroleum partners work to maximise the potential of the Jubilee and Tweneboa, Enyenra and Ntomme (TEN) fields.
These offshore assets remain important to the country’s oil production, domestic gas supply and wider energy sector. Corrections Policy
Despite the dispute, the government has emphasised that Tullow remains a key partner in Ghana’s petroleum industry and the country’s largest petroleum producer.
Tullow’s operations in the Jubilee and TEN fields support economic activity, employment and energy security.
The government therefore faces the task of enforcing the tribunal’s award while ensuring that the tax dispute does not unnecessarily disrupt petroleum production or discourage the investments needed to sustain operations.
According to Dr Forson, the government had already been engaged in discussions with Tullow before the tribunal issued its decision.

The discussions were intended to resolve outstanding tax matters amicably and are expected to continue following the ruling.
The negotiations will cover the assessment decided by the tribunal as well as separate proceedings relating to the disallowance of loan interest.
The latter remains a distinct matter and should not be confused with the claims resolved by the latest decision.
“The discussions are ongoing and would be resolved in the mutual interest of both parties,” the statement said. Editorial Ethics & Independence
The government has indicated that it intends to work with Tullow to implement the tribunal’s award in accordance with Ghanaian law.
In doing so, it will consider the need to maintain operations in the Jubilee and TEN fields and preserve the company’s ability to continue investing in the assets.
Dr Forson said the objective was to secure the revenue owed to the Ghanaian people while allowing Tullow to remain operational and financially capable of sustaining its activities in the country.
He also noted that Ghanaian law empowers the GRA to determine the time and manner in which assessed tax liabilities are paid.
This provides a framework for the authorities to pursue the tax revenue while considering the practical implications of payment arrangements.
The financial implications of the ruling will depend partly on how the award is implemented and the arrangements reached between the government and the company.
The separate loan-interest dispute also means that discussions between the parties are not yet complete.
For Ghana, the decision represents a major outcome in a high-value tax dispute involving a prominent international oil producer.
It also highlights the importance of clear tax administration, compliance with petroleum agreements and the enforcement of statutory obligations.
The government has maintained that recovering revenue due to the state and sustaining investment in the petroleum sector are not mutually exclusive objectives.
Its stated approach is to enforce the tribunal’s decision while preserving the conditions needed for continued production and investment in the Jubilee and TEN fields.